In this guide
What the difference means for a renter
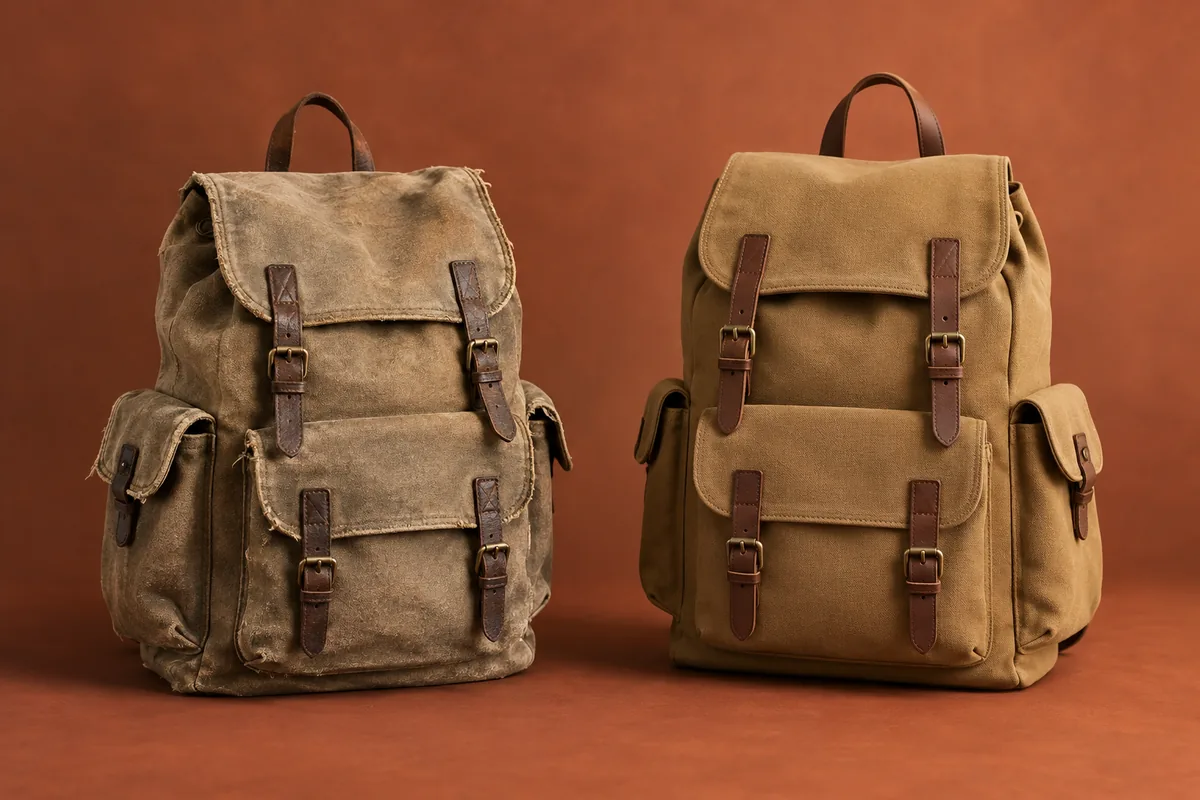
Replacement cost and actual cash value are ways of valuing eligible property after a covered loss. Actual cash value generally includes depreciation for age, use or condition. Replacement cost generally considers the current cost of a comparable new item, subject to the policy's settlement requirements. Neither method turns an excluded event into a covered claim.
This difference matters even when two quotes show the same personal property limit. That limit is a ceiling under the coverage, not a promise to pay the amount shown after any loss. Valuation, deductibles, special limits and replacement conditions still affect the result.
Start by separating three questions: was the cause of loss covered, how is the property valued, and what limits or deductions apply? Keeping those questions distinct helps you compare a policy without assuming that “replacement cost” means every expense will be paid immediately.
Actual cash value: understand the depreciation question
Actual cash value, often shortened to ACV, generally reflects the property's value with depreciation accounted for. The actual method depends on the policy and applicable rules. It is not necessarily the original purchase price, a number from an online resale advertisement or a fixed percentage you can apply to every possession.
A couch, laptop and coat can have different useful lives and conditions. Ask how the insurer evaluates the type of property involved. If you later receive a claim estimate, request an itemized explanation of replacement estimates, depreciation and other adjustments rather than trying to interpret one unexplained total.
For budgeting, think about the difference between receiving a depreciated settlement and buying working replacements. An older item can remain useful to you while having a lower depreciated value. That can leave a replacement expense you would need to cover yourself.
Replacement cost: comparable property, with conditions
Replacement cost generally uses the cost of a comparable new item rather than deducting depreciation from the final eligible settlement. “Comparable” matters. It does not automatically mean the newest premium model, an upgrade in quality or an unlimited shopping budget.
Ask whether replacement cost applies to personal property in the quote you are considering. A general advertisement about a policy's benefits may not identify the particular endorsement or eligible categories. Keep the relevant form with the declarations and check any exceptions.
Replacement cost can also involve reimbursement after you replace eligible property. North Carolina's insurance regulator explains that an insurer may initially pay actual cash value and later reimburse recoverable depreciation after replacement and receipt submission. Your own policy determines the process, deadlines and amount available.
A side-by-side example with the same loss
Consider a hypothetical covered loss involving several ordinary belongings. Assume comparable new replacements cost $4,000. For this illustration only, assume their combined actual cash value is $2,300, the deductible is $500, policy limits are sufficient and no other restriction changes payment.
| Calculation | Actual cash value | Replacement cost |
|---|---|---|
| Value used | $2,300 | $4,000 |
| Assumed deductible | $500 | $500 |
| Illustrative eligible settlement | $1,800 | $3,500 if replacement conditions are met |
| Difference from buying the $4,000 replacements | $2,200 | $500 after the full eligible settlement |
The difference between the two settlements is $1,700, the assumed depreciation in this example. Under a process that initially pays ACV, the replacement cost policy might begin with the same $1,800 payment and provide eligible additional reimbursement later. Do not assume that a replacement cost selection solves the immediate cash requirement.
These numbers illustrate arithmetic only. They do not estimate how any insurer would depreciate your property, whether repair would be appropriate, or what a real claim would pay. A special limit, excluded item or different replacement decision can change the calculation.
The original price is useful evidence, not the only number
Your original receipt helps identify what you owned and when you bought it. It does not automatically establish today's replacement cost or an ACV settlement. Prices and available models change, and the policy may consider repair or a comparable replacement rather than the exact discontinued model.
Imagine a hypothetical desk bought during a clearance sale. Record the purchase receipt and the desk's features, then research a reasonably comparable current item for your planning inventory. Keep those figures labeled separately. Combining purchase price and current estimates into one unlabeled column makes later conversations harder.
Likewise, do not assume a gifted or secondhand item has no replacement value simply because you paid little or nothing for it. Describe the actual item accurately and ask how the insurer would apply the policy. Ownership, condition and documentation still matter.
Build your contents estimate around the household you would replace
Start with a room-by-room inventory of comparable replacement costs. Include ordinary property as well as expensive electronics: clothes, shoes, bedding, cookware, small appliances and basic furniture. Do not use the amount you think the entire household would fetch in a yard sale as your only planning figure.
The belongings inventory tool can help organize categories and totals. Keep individual descriptions for important items and note where your figures are estimates. An inventory helps explain your coverage request; it is not an appraisal or approval of a future claim.
The renters insurance checklist adds a review of ownership, lease requirements and documentation. Revisit the list after a major purchase or move. Choosing replacement cost does not compensate for an inventory that omits half of your possessions.
Special property needs a separate conversation
Valuable jewelry, art, coins, collectibles and business property can have restrictions that differ from ordinary belongings. Some policies limit or exclude certain categories. Collectible value can also differ from the cost of an ordinary substitute. A general replacement cost endorsement may not resolve those issues.
For a rare item, tell the insurer what makes it valuable and ask about appropriate coverage, valuation and documentation. A professional appraisal may be relevant for specialized coverage. Keep the insurer's answer with any appraisal or receipt so you know which arrangement actually applies.
As a planning exercise, put a question mark beside every inventory item whose value depends on rarity, provenance or specialized use. Resolve those items separately from the everyday household total. This keeps you from assuming a large overall limit is sufficient evidence that each possession is fully protected.
A deductible is different from depreciation
Depreciation is part of determining value under the relevant settlement method. A deductible is a separate share of a covered loss under the policy. A replacement cost policy can still have a deductible, and an actual cash value settlement can be reduced by both depreciation and the applicable deductible.
For another hypothetical example, assume an otherwise eligible ACV loss is valued at $400 and the applicable deductible is $500. With no other relevant adjustment, the amount would not exceed the deductible. A larger personal property limit alone would not change that arithmetic.
When comparing renters insurance prices and deductibles, hold the deductible steady first. Otherwise, a price difference might reflect two separate changes: valuation and the amount you would absorb after a covered loss. Ask for revised options when the initial quotes are difficult to compare.
Ask about replacement deadlines before a loss
Request an explanation of how and when you must replace property to receive additional payment. Ask what notice, receipts or other proof are required and how a deadline is calculated. Avoid assuming a deadline you saw in another insurer's article applies to your policy.
Cash flow makes these questions practical. If replacing everything immediately would be difficult, ask what happens when items are replaced in stages. Also ask about selecting a less expensive substitute, repairing an item or deciding not to replace it. Different choices can affect the amount ultimately payable.
Write the answer in your own words and have the insurer confirm it if needed. “I receive an initial payment, then submit qualifying receipts before the stated deadline” is more useful than a note that simply says “RCV included.” Keep the actual policy wording alongside your notes.
Make the replacement order realistic
In your planning notes, separate immediate essentials from items you could replace later. A bed, work equipment and basic clothing may belong in the first group; decorative objects may belong in the second. This is your household's planning choice, not an instruction about the insurer's settlement order. Use it to ask how staged purchases and documentation would work under the actual policy before you need to rely on them.
Coverage for the cause of loss comes first
A valuation method is relevant only after the policy's coverage conditions are met. Replacement cost does not automatically insure flood damage, accidental breakage, wear or every missing item. Review the main renters coverage categories and common gaps alongside the valuation choice.
For a water incident, identify the source of the water and the damaged property before focusing on replacement prices. The renters water damage guide separates questions about sudden leaks, backups and flooding. Those distinctions may matter more than the age of the belongings.
For missing property, distinguish a reported theft from an item you cannot locate. The theft coverage guide discusses documentation and questions about off-premises property. A receipt can support ownership without establishing that the circumstances are insured.
How to compare two real quotes
Record the settlement basis beside each premium in the quote comparison worksheet. If a document is unclear, the policy-reading guide shows where to start and which details require the full contract.
- Confirm that both quotes address the same rental and household.
- Match the personal property limits and deductibles where possible.
- Identify whether personal property uses ACV or replacement cost.
- Check item restrictions and optional endorsements separately.
- Ask about payment timing and replacement requirements.
- Record the full policy-term premium difference.
- Review liability and temporary living expense coverage as separate decisions.
Then consider your own replacement budget. What could you buy quickly from savings? Which items are necessary for work, study or everyday living? This exercise will not predict a loss, but it makes the consequences of a lower initial settlement easier to understand.
Actual cash value may have a lower premium, while replacement cost can reduce eligible depreciation-related gaps. Ask for the actual options available to you rather than assuming the price difference. The better fit depends on coverage terms, affordability and your ability to fund replacements.
Questions renters often ask about settlement methods
Does replacement cost guarantee my full contents limit?
No. The limit is a maximum under the coverage, subject to the contract. The amount of the covered loss, eligible valuation, deductible and other terms determine payment. A policy limit is not a fixed benefit automatically payable whenever belongings are damaged.
Should I keep receipts for inexpensive items?
Keep reasonable documentation without making the inventory impossible to maintain. Photos, descriptions and available records can help explain your household. Ask your insurer what documentation it expects, especially for larger or unusual items. Do not assume that every missing original receipt automatically defeats a claim or that a photograph guarantees payment.
What if I disagree with a depreciation estimate?
Ask for the itemized basis and review whether the description, age, condition and comparable item are accurate. Supply relevant evidence through the insurer's claim process. If a dispute remains, ask about the policy's applicable procedures and your state insurance department's consumer assistance resources.
Make the choice before you need the coverage
The useful decision is more specific than checking a box labeled replacement cost. Confirm what property qualifies, how it is valued, what you must pay yourself and what you must do to receive any later reimbursement. Keep that explanation with your inventory.
When you are ready to organize an application, use the renters quote preparation guide. It helps gather information without implying that a quote or checklist activates coverage. Your insurer must confirm the actual policy, effective date and terms.
Sources and References
- North Carolina Department of Insurance: Actual Cash Value vs. Replacement Cost Value
- Texas Department of Insurance: Replacement cost or actual cash value
- Texas Department of Insurance: Extra coverage for collectibles
- Texas Department of Insurance: What to know about deductibles
- NAIC: Home Inventory
- NAIC: Renting Your Home? Protect Your Belongings with Renters Insurance
- Oregon Division of Financial Regulation: Consumer guide to renters insurance