In this guide
Water damage coverage depends on where the water came from
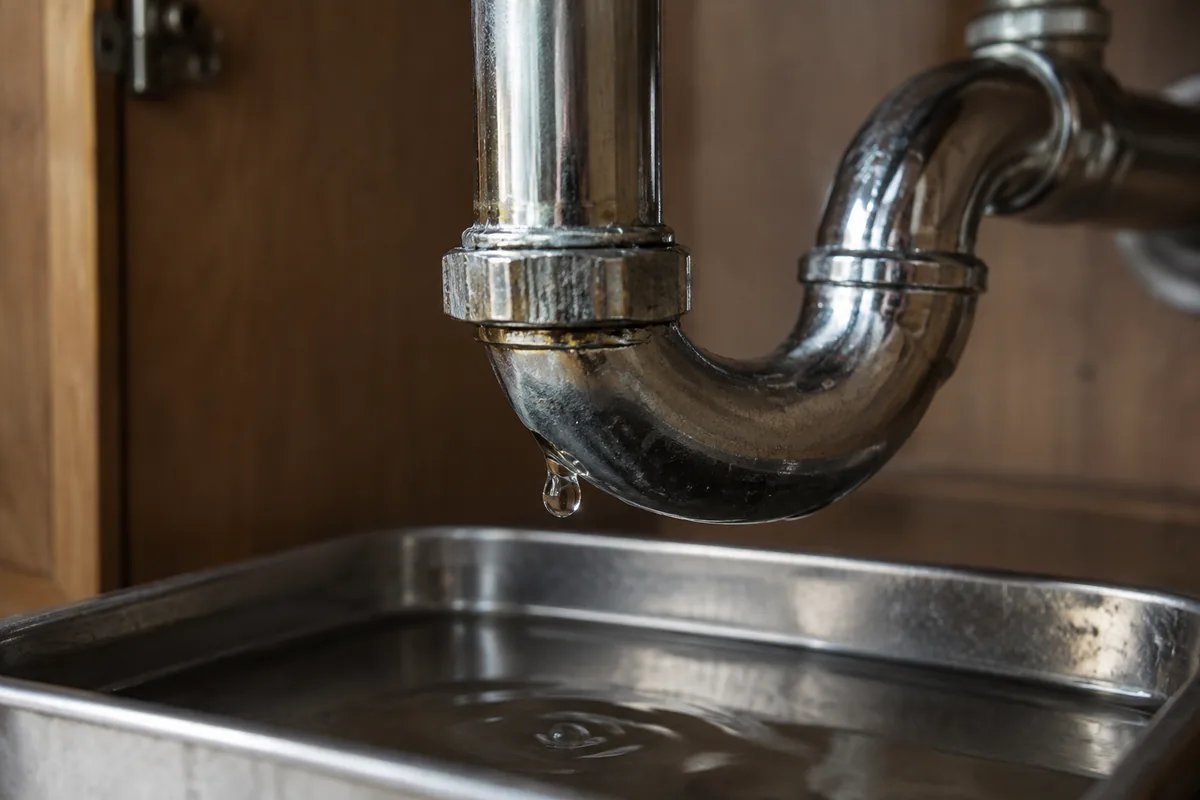
A burst supply line, a leaking ceiling and water entering under the front door can leave the same wet belongings. They do not necessarily create the same insurance claim. Describe the event accurately, including what you know and what remains uncertain. Your insurer must consider the cause, affected property and policy language before deciding whether coverage applies.
Start with three questions: What caused the water? Which damaged items belong to you? Does the policy cover that cause and those items? Then review the deductible, settlement method and any special limits. The renters insurance coverage guide explains how belongings, liability and additional living expenses fit together.
The Texas Department of Insurance explains that sudden, accidental water damage is commonly covered, while gradual leaks often are not. That distinction is useful, but it does not turn every fast-moving water event into a covered loss. A sudden storm flood, for example, raises a different coverage question from a suddenly broken pipe.
Compare common apartment water damage situations
| Situation | What to ask the insurer |
|---|---|
| A pipe or appliance hose suddenly breaks | Is the resulting damage to my belongings covered, and what conditions apply? |
| A pipe leaks repeatedly over time | How do seepage, repeated leakage and maintenance exclusions apply? |
| Water backs up through a sewer or drain | Do I have a water-backup endorsement, and what limit and deductible apply? |
| Surface water rises into the apartment | Does a separate flood contents policy cover this event and location? |
| Rain enters after a storm damages the building | What conditions govern rain entering through a damaged roof or wall? |
| Mold develops after an incident | How are damaged belongings, testing and remediation treated separately? |
Use the table as a discussion aid, not a coverage verdict. Keep a copy of the actual forms or endorsements that answer your questions. A marketing phrase such as water protection cannot explain the differences between these situations.
Burst pipes and leaks from an upstairs apartment
Water released accidentally from plumbing or an appliance may damage your furniture, clothes and electronics. Your renters insurer can review those belongings even when the water originated elsewhere in the building. You do not need to establish every detail of a neighbor's responsibility before telling your own insurer what happened.
Hypothetical example: an upstairs washing-machine hose fails while you are away. Water reaches your bedroom and damages a mattress, dresser and clothes. Photograph the affected items when safe, notify management and report the event to your insurer. Ask whether those items can be cleaned or repaired and how replacement would be valued. Do not assume the landlord's repair schedule also controls your personal-property claim.
For frozen pipes, ask about policy conditions concerning heat and reasonable precautions. If you will leave the rental vacant during a trip, follow the lease and building instructions and discuss any insurance obligations in advance. Do not shut down required heating simply because you will be away.
Your contents and the landlord's building are different
Your mattress and desk are different insurance interests from the building's drywall, plumbing and permanent flooring. Renters insurance generally addresses your insured belongings rather than insuring the entire structure. Tell both management and your insurer when an event affects both. Reporting a maintenance problem is not the same as notifying the insurer of your loss.
Make two lists before discussing repairs. Put your damaged possessions on one and building damage you observed on the other. Include ownership questions for items such as a washer, shelving or installed improvements. If you share the apartment, record whose belongings were affected; the roommate coverage guide explains why one resident's policy should not be assumed to insure everyone.
If management says you owe for building repairs, send the demand to your insurer promptly. Liability for damage to rented property has its own exclusions and exceptions. Whether you caused an incident and whether an insurance policy covers it are separate questions. Do not assume every repair bill becomes an insured liability claim.
Why gradual leaks and water backup need separate attention
A slow drip behind a cabinet can create extensive damage before anyone discovers it. Keep a factual timeline: when you first noticed a stain, odor or damp item; when you contacted management; and what repairs followed. Ask how the policy treats hidden damage and reporting requirements. The date of discovery alone does not establish the date or duration of the leak.
Water backup is another distinct issue. Some insurers offer an optional endorsement for certain sewer, drain or sump-related losses. Ask whether it is available for your rental and whether it protects contents, additional living expenses or both. A landlord's endorsement does not automatically extend to your belongings, and an endorsement may have a lower limit than your general contents coverage.
When comparing options, write down the additional premium, covered causes, exclusions, limit and deductible together. This makes it easier to decide what the option actually adds. Use the same approach when reviewing renters insurance costs and deductibles, rather than treating the lowest monthly payment as the whole comparison.
Flood insurance for renters protects a different risk
Standard renters policies generally exclude flood. The National Flood Insurance Program offers contents coverage for eligible renters, separate from a building owner's flood policy. You can ask an insurance professional about that option without owning the apartment building. Availability, coverage details and the effective date still need confirmation.
NFIP contents coverage has its own valuation rules, restrictions and deductible. Ask specifically about possessions stored in a basement or below the lowest elevated floor. Do not assume the entire apartment inventory receives the same treatment wherever it is stored. NFIP coverage also excludes temporary housing and additional living expenses.
Ask when flood coverage can begin before an approaching weather event. NFIP policies commonly have a waiting period, with specified exceptions. Private flood policies may have different terms. Neither buying a new policy nor increasing a limit should be treated as a way to insure damage that has already happened.
Will renters insurance pay for a hotel after a leak?
The temporary-housing guide explains the difference between planning expenses and establishing coverage. Our housing expense planner keeps normal and additional costs separate; its total is not a reimbursement estimate.
Additional living expense coverage may help when a covered event makes your rental uninhabitable. It generally addresses reasonable extra expenses above your usual living costs, within policy limits and conditions. Having water damage does not automatically qualify every hotel stay, meal or moving expense.
Before making a long booking, ask the insurer what it will authorize, what records it needs and how the dollar and time limits work. Explain practical needs such as accessibility, proximity to work or space for children. If you have an animal, ask about acceptable accommodation and related extra costs; our pet-owner guide covers other insurance questions to review.
Keep a separate expense log with dates, reasons and receipts. Record normal expenses as well so you can explain the increase. Hypothetical example: if your usual food spending is $90 over a particular period and comparable temporary arrangements cost $145, the extra amount is $55. That arithmetic illustrates an increase; it does not establish an insurer's reimbursement.
How to document damaged belongings
A useful claim record identifies the item, its condition before the incident, how it was damaged and the supporting evidence available. Start with broad room photographs, then document individual items. Add brand, model, approximate age and receipts where available. Explain any estimate instead of presenting it as an exact original purchase price.
- Follow emergency instructions and avoid electrical hazards, contaminated water and unstable areas.
- Notify the landlord and insurer promptly using the known facts.
- Ask what immediate steps are safe and reasonable to prevent further damage.
- Keep a dated list of damaged belongings and supporting photographs.
- Ask the adjuster what to retain and how to document anything that must be discarded for safety.
- Save cleanup, temporary protection and accommodation receipts separately.
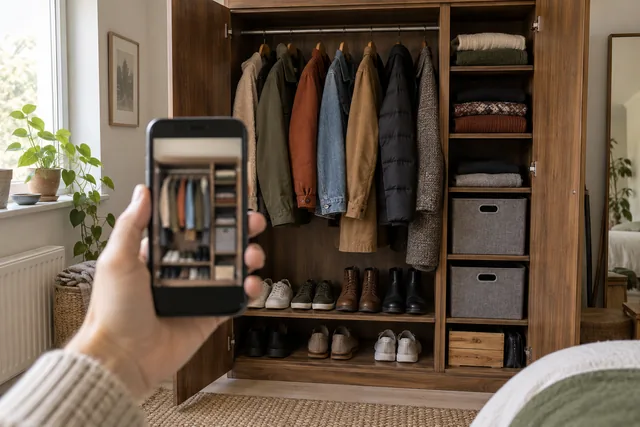
The belongings inventory tool can help organize categories before a loss. Keep your saved records somewhere accessible if your phone or computer is damaged. Avoid relying on one device as the only copy of both your photographs and your insurance information.
How the deductible and valuation affect your claim
Coverage for the cause does not establish the amount payable. An insurer may consider repair, replacement, depreciation, limits and the applicable deductible. Replacement cost coverage can also have replacement and documentation requirements. The replacement cost and actual cash value comparison explains why the same damaged item can produce different payments.
Hypothetical example: assume a covered collection of belongings has an accepted value of $2,800, an applicable $500 deductible and no other adjustments. The illustrative payment would be $2,300. This is arithmetic using stated assumptions, not a claim estimate. Actual settlement may involve different values, category limits or staged reimbursement.
Review the contents limit using the cost of replacing your entire household, not just the items closest to a sink. Water can move between rooms. Clothing, books, linens and everyday kitchen equipment can add substantially to a loss even when no single item seems expensive.
Keep the cause and claim records organized
Use a simple event log after an incident. Record the discovery time, the rooms affected, your report to management, the insurer's claim number and each follow-up conversation. Add any written explanation from the plumber or building manager without changing its wording to match what you think insurance will cover. If explanations conflict, send both to the adjuster and ask what additional information is needed.
Separate estimates from completed work and separate your expenses from the landlord's expenses. Label photographs by room and date so the adjuster can connect them with your item list. If the insurer excludes an item or declines part of the claim, ask for the explanation and relevant policy wording in writing. You can then compare the decision with the facts already provided and identify any missing information. An organized record helps you ask precise follow-up questions; it does not guarantee a particular decision or speed of payment.
Questions to ask before you choose a policy
Use the renters insurance checklist to bring your inventory and policy questions together. For water concerns, request answers to these specific points:
- Which sudden water events are covered for my personal property?
- How does the policy address repeated leaks and hidden damage?
- Is water-backup coverage included, optional or unavailable?
- What restrictions apply to mold, testing and cleanup?
- What makes an event eligible for additional living expenses?
- Are there special deductibles or smaller water-related limits?
- Should I consider separate flood contents insurance for this rental?
Keep the answers with your quote and compare them with the issued policy. If an answer only repeats that water damage is covered, ask the representative to identify the relevant exclusion or endorsement. A specific answer is more useful than a broad reassurance.
Common questions about renters insurance and water damage
Does my landlord have to replace my belongings after a leak?
Do not assume the landlord's property policy covers your possessions. Responsibility can depend on the facts, lease and applicable law. Notify your own insurer and provide management's information without trying to settle those separate issues yourself.
Is mold automatically covered when a pipe breaks?
No blanket answer applies. Coverage for an item damaged by a covered event can differ from coverage for mold inspection or remediation. Ask about the underlying cause, exclusions, limits and required actions after discovering the water.
Can I buy renters insurance after discovering water damage?
You can discuss coverage for future events, but a new policy does not retroactively cover an earlier loss. Describe any existing damage accurately on the application and confirm the actual effective date before relying on the new policy.
When it is safe to document a loss, follow the claims preparation checklist to organize evidence, receipts and insurer questions. It does not determine whether a particular water event is covered.
Sources and References
- Texas Department of Insurance: Water damage and mold coverage
- FEMA National Flood Insurance Program: Buying a flood policy
- Texas Department of Insurance: Additional living expenses
- Progressive: Does renters insurance cover water damage?
- Oregon Division of Financial Regulation: Renter insurance
- North Carolina Department of Insurance: Actual Cash Value vs. Replacement Cost Value
- Texas Department of Insurance: Creating a home inventory
- Texas Department of Insurance: What to know about deductibles