In this guide
Start with people, then paperwork
A fire, break-in, or serious leak can leave you trying to solve several problems at once. You do not need a perfect inventory before taking the first step. Get yourself, other household members, and pets away from immediate danger. Call emergency services when needed and follow official instructions about entering the building.
Do not enter standing water, handle electrical equipment near water, or re-enter an unsafe apartment to collect insurance documents. Tell the insurer if you cannot safely access the unit. Photographs and paperwork can wait for safe access; they should never become a reason to put yourself at risk.
This guide is general education for renters with a loss. Your contract, insurer's instructions, and applicable state law determine the duties, deadlines, and coverage that apply. Completing a checklist does not report a claim or guarantee payment.
Find the actual insurer and report the loss
Use the claims number or official reporting channel shown in your policy documents. The apartment portal, insurance seller, and company responsible for paying covered claims may be different organizations. Our guide to checking a renters insurance company explains how to identify the insurer behind a brand.
Contact the insurer promptly instead of waiting until every loss is counted. Give the insured name, rental address, policy number if available, approximate time of the event, and a factual description. Say when a detail is unknown. Ask what the insurer needs next and how to send documents securely.
Record the claim number, assigned contact, and a reliable way to reach you while displaced. Ask whether a call is being recorded as a coverage inquiry or a filed claim if that distinction matters to your question. Do not let that question delay required notice of a loss.
Notify the property manager separately
Tell the landlord or property manager about building damage and immediate maintenance needs using the lease's reporting procedure. Save a copy of the notice. Reporting a leaking pipe to maintenance does not necessarily report a personal belongings claim to your insurer, and notifying your insurer does not replace necessary notice to management.
Keep the two workstreams distinct: the building's condition and your belongings, temporary expenses, or potential liability. Ask management about access and repair arrangements. Lease obligations and tenant rights vary, so do not assume an insurance claim automatically changes rent obligations or ends the lease.
Record what you observed without deciding the cause
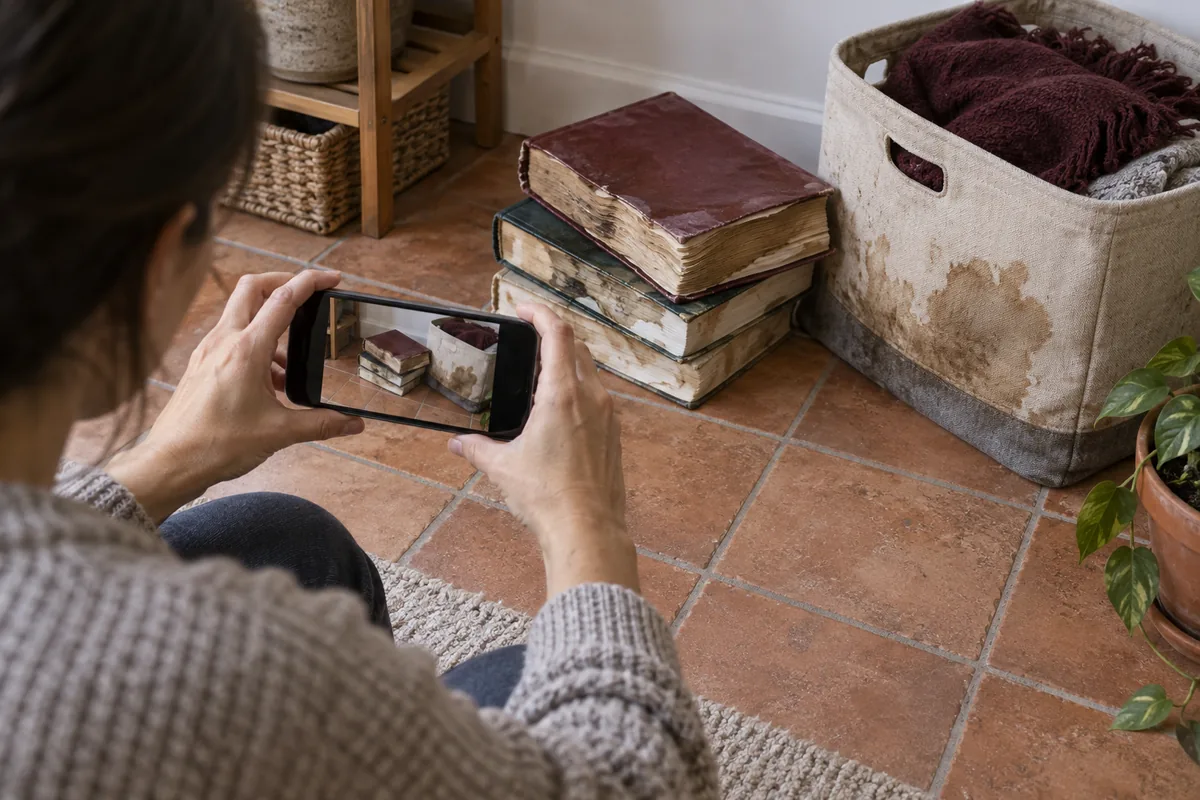
When access is safe, take overall room photos before close-ups of individual items. Capture visible damage, where the item was, and identifying labels when accessible. A brief video can explain the layout, but still photos make individual details easier to find. Keep the original files.
Write a short timeline while the sequence is fresh: when you left, when you discovered the problem, whom you contacted, and what happened next. Separate observation from inference. “Water was dripping from the ceiling above the desk” is more useful than claiming a plumbing diagnosis you cannot confirm.
The water damage guide explains why the source and circumstances matter. A wet item is evidence of damage; by itself, it does not establish a covered cause. Give the adjuster maintenance reports or other available records without changing their wording.
For theft, keep the police and insurance records aligned
Report theft or another suspected crime to the police through the appropriate emergency or nonemergency channel. Ask how to obtain the report or incident number, then give that information to the insurer. Follow any instructions about preserving the scene.
Create one working list of missing items and date each revision. If you later find something, correct the records with both organizations as appropriate. Do not add a guessed serial number to make a list look complete. Our renters theft guide covers questions about belongings away from home and special limits.
Limit further damage safely and preserve evidence
Take safe, reasonable temporary steps to protect belongings without waiting for an insurer reply when delay would allow further damage. Contact the insurer promptly for instructions and document what you do. Coordinate building work with the property manager. Avoid attempting hazardous cleanup or repairs beyond your skills or authority. Save receipts and document the work, who performed it, and why it was necessary.
Ask before permanent repairs or disposal that would prevent inspection. Never keep unsafe food, contaminated material, or another dangerous item solely for insurance evidence. Follow health and emergency instructions, photograph items when safe, record why disposal was necessary, and notify the adjuster. Ask what alternative documentation is acceptable.
Keep temporary mitigation expenses separate from replacement purchases. Label the receipt categories in your records. The fact that spending was urgent does not establish reimbursement, so ask about covered work and approval arrangements as soon as practical.
Build a loss inventory one room at a time
Start with an existing inventory, photos, purchase history, or saved receipts. List the items actually affected, not every possession you own. Include brand, model, approximate age, quantity, ownership, and the kind of damage or loss. Mark estimates as estimates and leave unknown facts clearly identified.
The belongings inventory tool helps organize category totals, but a claim may require an itemized format supplied by your insurer. Ask for that format early. A household planning total is not the same as a submitted proof of loss.
If receipts are missing, ask which other records the insurer will consider. Order confirmations, photographs showing the item, bank records, manuals, or gift information may help explain ownership. Their usefulness depends on the claim; do not assume any one substitute automatically satisfies the requirement.
A simple record for each affected item
| Field | What to record |
|---|---|
| Identification | Item name, quantity, brand, model, and known serial number. |
| Ownership and history | Owner, approximate purchase date, and known original price. |
| Loss details | Location, observed damage, or why the item is missing. |
| Supporting records | Photo filenames, receipts, and comparable replacement references. |
| Status | Submitted, questioned, corrected, or awaiting instructions. |
Give each item a short reference such as Bedroom-01 and use it in related filenames. This is an organizational suggestion, not an insurer requirement. Avoid double counting a shared item or treating borrowed property as something you own.
Ask about temporary housing before costs accumulate
If you cannot stay in the rental, ask whether additional living expenses coverage applies to this event. Discuss the lodging arrangement, spending limits, duration, documentation, and whether an advance is available. A need for accommodation alone does not establish coverage.
Keep receipts from the beginning. Separate ordinary spending from additional costs caused by displacement. In a hypothetical example, spending $45 on meals instead of the usual $20 creates a $25 increase to discuss, not an automatic $45 reimbursement. The insurer determines eligible expenses under the policy.
Use the temporary-housing expense planner to organize estimates and the temporary-housing guide to prepare questions. Keep normal rent obligations as a separate issue to resolve with management and appropriate advice.
Set up a small claim folder you can maintain
Create a folder with separate sections for the policy, incident timeline, belongings, expenses, and correspondence. Use filenames you can understand later, such as a room name followed by an item reference and date. Keep a working list of what each file shows so an unfamiliar reviewer can follow the connection.
For a hypothetical damaged desk, the record might connect Desk-01 to a room photograph, a close-up of damage, an order confirmation, and a comparable product description. Explain when a replacement reference differs from the original. A current listing is a comparison aid, not proof that the insurer owes that advertised price.
If another household member helps, agree who updates the master list. Keep older versions instead of overwriting the only copy, and note corrections. Send a clear updated version when requested so the adjuster does not have to decide which of several conflicting lists is current.
For each expense, write down the date, purpose, amount, and receipt reference. Add a separate status such as submitted, awaiting answer, approved, or paid. Those labels describe the record you have; use approved only when you actually have approval. Recording an amount as submitted should never make it appear that the insurer has accepted it.
You can use paper, a spreadsheet, or a secure digital folder. Choose the system you can keep current while handling everyday needs. A simple reliable record is more useful than a complicated system that becomes another unfinished task.
Read the policy alongside the adjuster's instructions
Locate the declarations, policy wording, and endorsements that applied on the loss date. The declarations summarize important amounts but do not contain every exclusion or condition. The policy-reading guide helps you navigate these documents without mistaking the summary for the full contract.
Ask which deductible, personal property limit, and special item limits apply. Confirm whether affected belongings are valued using actual cash value or replacement cost terms. Actual cash value considers depreciation; replacement cost provisions concern comparable replacement and can include conditions before the full amount becomes payable.
Request an itemized explanation of any depreciation, limit, or other deduction. If replacement receipts are needed for an additional payment, ask about the required evidence and deadline before making purchases. The settlement-method comparison explains the basic distinction.
Keep deadlines in a written task list
Ask the insurer to identify required forms, proof-of-loss instructions, inspection arrangements, and submission dates. Put each task in your calendar with the source of the instruction and the person responsible. There is no single nationwide deadline that fits every renters claim.
If you cannot meet a requested date, contact the insurer before it passes and request written clarification or an extension. Do not assume silence grants additional time. An insurer's response deadline, your document deadline, and any legal filing deadline can be different. Seek qualified help promptly if legal rights are at stake.
Make follow-up easier with a communication log
For each call or message, note the date, person's name, topic, documents requested, and promised next action. Keep copies of submissions and confirmations. When uploading photos, record which files went through successfully instead of assuming an upload screen proves every file arrived.
A useful follow-up can be brief: “I sent items Bedroom-01 through Bedroom-08 on the date shown in the confirmation. Please confirm whether you need any additional information about those items.” Clear references let the recipient locate the issue without rereading your entire claim.
Share claim documents only through verified channels. The printable checklist provides writing spaces for your own private copy. RentersInsurance.ai does not receive your completed worksheet or submit a claim for you.
Review the decision and ask focused questions
Compare the insurer's explanation with your item list and policy terms. Ask about omitted items, incorrect quantities, or an unclear valuation. If coverage is declined, request the written reason and the policy provisions relied on. Supply corrections and supporting information through the stated review process.
If concerns remain, contact your state's insurance department for information about its complaint process. Organize the policy, decision, timeline, and relevant correspondence. A complaint is not a promise of additional payment, and it should not be assumed to extend other deadlines.
Use the checklist to choose your next manageable step
Open the printable after-loss checklist and mark what is complete, what needs an answer, and the next follow-up date. You can make progress without finishing every category today. Prioritize safety, required notice, and time-sensitive requests before organizing the remaining records.
After the immediate claim tasks settle, refresh the inventory and review changed belongings or living arrangements. The coverage-review reminder tool can create a calendar reminder for that future review. It is separate from claim deadlines and does not replace the dates supplied by your insurer.
Sources and References
- Washington Office of the Insurance Commissioner: Steps after home damage or a loss
- Texas Department of Insurance: Help after a storm
- Idaho Department of Insurance: Home and renters claims
- Texas Department of Insurance: A home inventory
- Texas Department of Insurance: Additional living expenses
- NAIC: Actual cash value and replacement cost coverage
- NAIC: A Consumer’s Guide to Home Insurance
- NAIC: Filing complaints and researching insurance carriers